New Mexico UM/UIM Claims: What Injured Drivers Should Know
Peter Romero | Oct 01 2026 14:00
Quick Summary:
New Mexico has one of the highest uninsured-driver rates in the country, with an estimated 24.1% of motorists uninsured in 2023. If an uninsured or underinsured driver hurts you, uninsured/underinsured motorist (UM/UIM) coverage on your own policy may help pay for your injuries. I can review the facts, your policy, and every possible source of coverage so you are not left carrying the cost of someone else’s mistake.
I’m Peter Romero, and I have spent more than 25 years helping injured New Mexicans after serious crashes. A collision is stressful enough. It becomes even more frustrating when the driver who caused it has no insurance, disappears from the scene, or has only a small policy that will not come close to covering medical bills, lost income, and the real impact of an injury.
Why UM/UIM Coverage Matters in New Mexico
New Mexico drivers must carry liability insurance, but the current minimum limits are only $25,000 for injury or death to one person, $50,000 for injury or death to two or more people in one crash, and $10,000 for property damage. Those limits can be exhausted quickly after an emergency-room visit, imaging, follow-up care, physical therapy, or time away from work.
That is where UM/UIM coverage can matter. UM stands for uninsured motorist coverage. UIM stands for underinsured motorist coverage. In simple terms, this is coverage you buy to protect yourself, your household, and in many cases occupants of your insured vehicle when the at-fault driver has no usable insurance or not enough insurance.
New Mexico law requires insurers to offer UM/UIM coverage with auto policies, generally up to the liability limits you select. A named insured can reject it, but that rejection must be in writing and made part of the policy. Whether coverage exists, who is insured, and how much is available are questions worth reviewing carefully—not guessing about after a crash.
How an Uninsured Motorist Claim Can Help
An uninsured motorist claim may apply when the driver who caused your injuries had no liability policy at all, when that insurer denies coverage, or when the responsible vehicle was a hit-and-run vehicle under the applicable policy and New Mexico rules. This is not a claim against the driver who hurt you alone. It is often a claim under your own insurance contract.
That can feel uncomfortable. You have paid premiums and may expect your insurer to be on your side. But once a significant claim is made, the insurer still examines fault, medical records, treatment, prior injuries, and damages. I tell clients not to assume an adjuster’s first answer is the final answer.
UM/UIM benefits may help compensate for medical expenses, future care, lost wages, reduced earning ability, pain and suffering, and other losses caused by the crash, subject to the policy terms and available limits. The details matter. So does acting early enough to preserve evidence and give proper notice.
When the Other Driver Is Underinsured
Underinsured does not mean uninsured. It means the at-fault driver has liability coverage, but the available limits are too low to fully compensate you for your damages. For example, a driver may carry the New Mexico minimum of $25,000 per person. A serious neck, back, brain, orthopedic, or other injury can easily exceed that amount.
UIM claims can be more complicated than people expect. The other driver’s policy, settlement terms, your own UM/UIM limits, and the wording of your policy can all affect the recovery. Before accepting a settlement or signing a release with the at-fault driver’s insurer, it is important to understand how that decision may affect your own coverage.
At Peter Romero Injury Lawyer, I look beyond the first insurance card handed over after a crash. I review the available liability insurance, UM/UIM coverage, vehicle ownership, work-related coverage, and other facts that may identify additional insurance.
What “Stacking” May Mean for Your Claim
Stacking is a legal and insurance term for adding together UM/UIM coverage from more than one insured vehicle or policy, up to the amount of your damages and subject to the applicable rules. As a basic example, a person who has UM/UIM coverage on two vehicles and pays separate premiums may have more protection than the single per-vehicle limit suggests.
Stacking is not automatic in every situation, and insurance policies can contain important selection, rejection, and limit language. New Mexico courts have recognized strong protections for insured people who paid for UM/UIM coverage, while also addressing when a person made a valid decision about coverage. The New Mexico Office of the Superintendent of Insurance now requires insurers to use per-vehicle UM/UIM disclosure and exclusion forms for new applications and policy changes.
Do not let the word “stacking” discourage you. Bring in your declarations pages and policy documents. I can help determine whether more than one coverage limit may be available.
Hit-and-Run Crashes Require Fast Action
A hit-and-run crash can leave you shaken, injured, and worried that there is no claim because the driver cannot be found. That is not always true. UM coverage can include certain unknown-driver claims, but prompt reporting and evidence are especially important.
New Mexico’s standard UM rules address hit-and-run vehicles that cause injury or property damage through physical contact or attempted physical contact. They also require prompt reporting: generally, report the crash within 24 hours to law enforcement or the Motor Vehicle Division, and provide the insurer a sworn statement within the required timeframe. Your individual policy may provide broader protection, but you should not wait to find out.
Call 911 when appropriate, get medical attention, photograph the scene and vehicle damage, collect witness information, preserve dash-camera footage, and report the claim promptly. Even if another vehicle forced you off the road without a direct collision, have the facts reviewed right away.
If Your Own Insurer Pushes Back
Your own insurer may question whether the other driver was at fault, whether the driver was truly uninsured, whether you rejected UM/UIM coverage, whether an injury was caused by the wreck, or whether a policy exclusion applies. It may request records, a recorded statement, or an examination under oath.
Be truthful, but do not rush into a recorded statement, settlement, or release without understanding the consequences. Keep copies of every letter, email, medical bill, estimate, and policy document. Follow through with reasonable medical care. Most importantly, do not assume a denial is correct just because it came from an insurance company.
At Peter M. Romero & Associates, P.C., I personally review the coverage issues and explain them in plain language. You can speak directly with me about what happened, what the insurer is saying, and what steps make sense for you.
FAQ
Is UM/UIM coverage required in New Mexico?
Liability insurance is required. Insurers must offer UM/UIM coverage, but a named insured may reject it in writing. The policy and rejection paperwork should be reviewed closely.
Can I make a UM/UIM claim if I was a passenger or pedestrian?
Possibly. Coverage can extend beyond the person driving the insured car. It depends on the policy, your relationship to the named insured, the vehicle involved, and the facts of the crash.
Will using my own UM/UIM coverage raise my insurance rates?
Rate questions are policy- and insurer-specific. Do not avoid reporting a serious claim simply because of a fear about premiums. First, understand the coverage you purchased and the losses you are facing.
What should I bring for a coverage review?
Bring your declarations page, policy, crash report, photos, correspondence from insurers, medical records or bills you have received, and any settlement offer. I will help identify what is missing and what should be reviewed next.
Do I need a lawyer for an uninsured-driver claim?
Not every claim requires a lawyer, but legal help is especially valuable when injuries are significant, coverage is disputed, a hit-and-run occurred, or the other driver’s limits are not enough. Learn more about our work with Car Accidents
and broader Personal Injury
claims.
If an uninsured, underinsured, or hit-and-run driver injured you anywhere in New Mexico, call Peter Romero Injury Lawyer at (505) 900-9000 for a free review of your coverage. You pay nothing unless I win your case.
About the Author
Peter M. Romero | Attorney
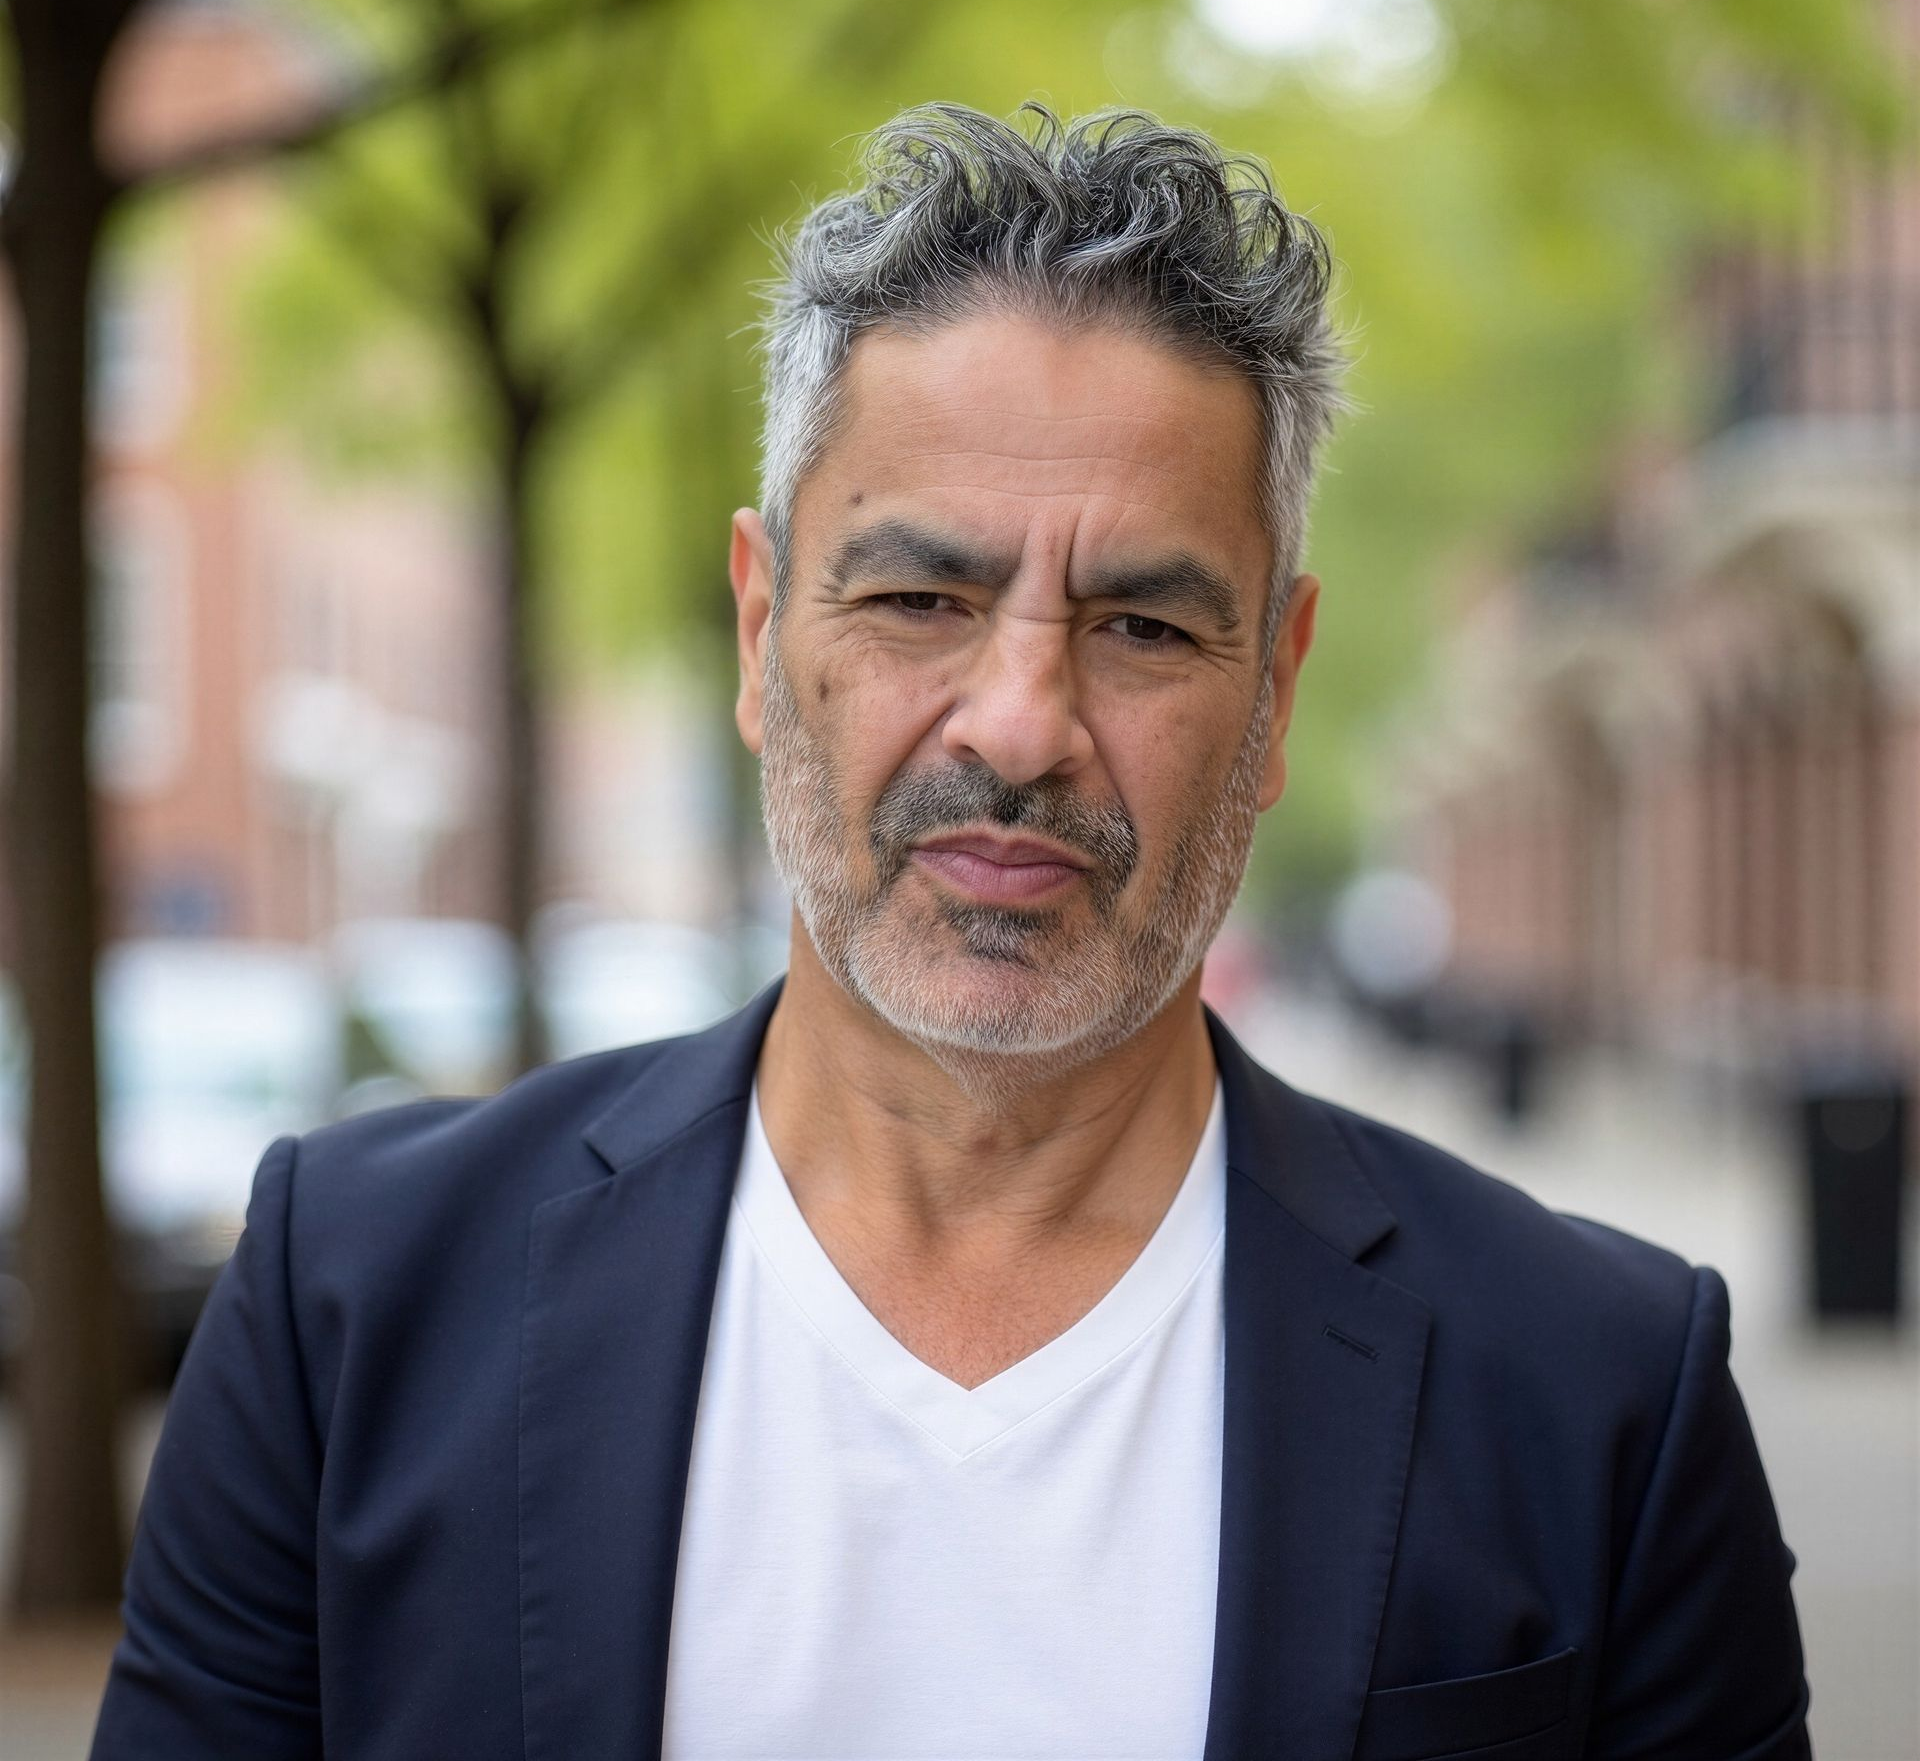
I’m Peter Romero, a personal injury lawyer born and raised in New Mexico. I went to school here, earned my law degree here, and I’ve spent the last 25 years fighting for injured New Mexicans and their families, recovering millions of dollars for my clients along the way. I write this blog to give you straight answers about New Mexico injury law, without the legal jargon. If you’ve been hurt and have questions about your situation, call me at (505) 900-9000. You’ll talk to me, not a call center.